Overview of the Oak Barrels Market scope and industrial significance
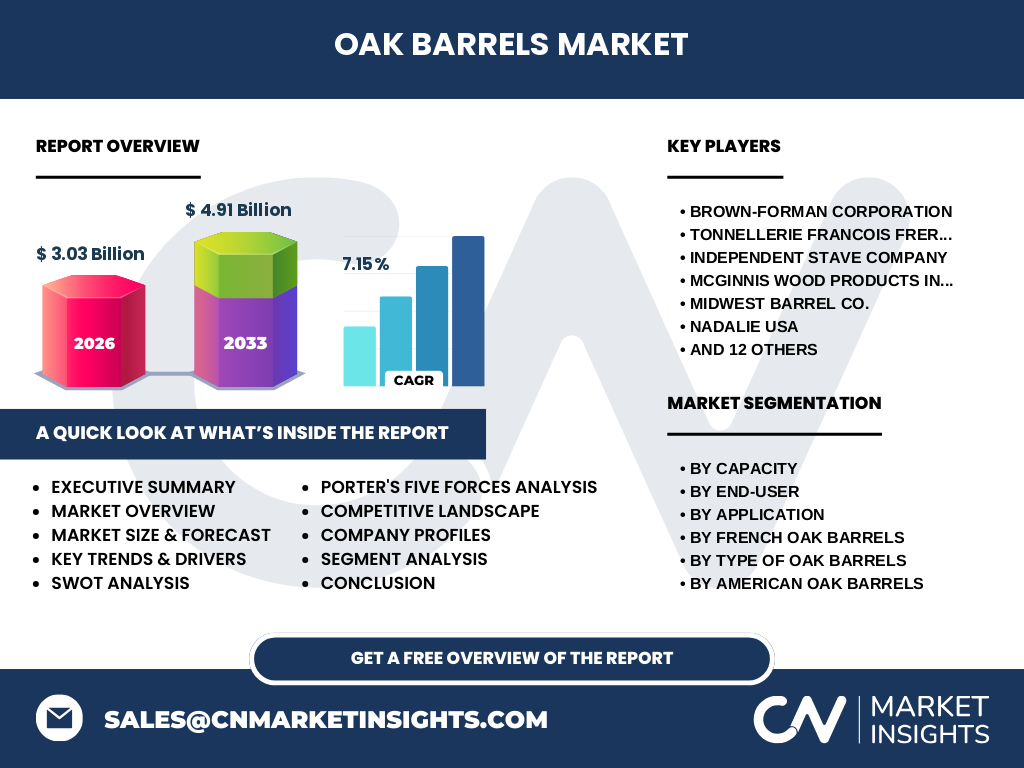
The Oak Barrels Market serves as the backbone of premium beverage maturation, facilitating the chemical evolution of flavor profiles in wine, whiskey, and beer. Spanning from artisanal wood-craft to industrial cooperage, this sector is critical for maintaining organoleptic standards in global trade. Valued at 3.03 Billion in 2026, the market acts as a vital bridge between forestry output and the high-value alcohol export economy.
Structural Growth Drivers and Market Constraints
Market expansion is fueled by the premiumization of spirits, particularly in the craft bourbon sector, which drives demand for charred American oak barrels. Conversely, the market faces significant logistical hurdles, including the rising cost of raw timber and stringent sustainability certifications required by regulatory bodies like the FSC. Balancing high-quality wood availability with shifting consumer demand for sustainable aging vessels remains the core strategic challenge for cooperages.
Emerging Trends and Strategic Pattern Shifts
We are witnessing a shift toward experimental aging technologies, where distillers utilize hybrid oak barrels or specialized toasted French oak barrels to achieve unique flavor profiles. There is an accelerating demand for customized barrel solutions, such as size-specific options for pilot-scale brewing, enabling smaller brands to innovate faster than traditional, large-scale production facilities could previously facilitate.
COVID-19 Impact and Long-Term Recovery Trajectory
The pandemic initially disrupted the Oak Barrels Market due to global supply chain bottlenecks at key ports. However, the subsequent home-consumption surge accelerated the demand for high-end spirits and craft wine. Our analysis indicates that the sector has moved past recovery into a resilient growth phase, as distilleries ramp up capacity to meet the sustained demand for aged, premium-labeled products.
Competitive Landscape and Strategic Dynamics
Market concentration is dominated by major stakeholders such as Brown-Forman Corporation, Tonnellerie Francois Freres (TFF), and Independent Stave Company. These industry leaders leverage deep-rooted relationships with stave mills and global distribution networks. The competitive intensity is high, with companies like Nadalie USA and Bouchard Cooperages focusing on niche, high-end boutique winery segments to maintain premium pricing power despite fluctuating commodity costs.
Executive Summary: High-level synthesis of market findings
The Oak Barrels Market is poised for substantial expansion, with a projected market size reaching 4.91 Billion by 2033. Driven by a CAGR of 7.15%, the industry is transitioning from a commodity-based supply model to a specialized, innovation-driven ecosystem. Success hinges on a company's ability to balance traditional cooperage craftsmanship with the operational agility required to serve both large-scale commercial distilleries and craft beverage start-ups.
Market Forecast: 2027 to 2033 Projections
Between 2027 and 2033, the market will experience consistent growth, scaling from its 2026 baseline of 3.03 Billion to a valuation of 4.91 Billion. This 7.15% CAGR is underpinned by increased infrastructure investment in emerging markets and the continued dominance of the spirits aging segment, particularly within the small-batch bourbon and premium aged-wine sectors across North America and Western Europe.
Segmentation Analysis and Market Roles
The market is segmented by capacity (Small up to 100L, Medium 100-500L, Large over 500L) and end-user (Wineries, Distilleries, Breweries). Medium-capacity barrels remain the industry standard for traditional aging, while small-capacity barrels are seeing rapid adoption among craft innovators. This stratification allows producers to optimize their inventory based on the specific turnover requirements and maturation timelines of the wine, spirits, and beer industries.
Regional Market Performance and Geographic Distribution
Regional performance is strongly correlated with localized beverage production heritage. Europe, anchored by traditional French and Hungarian oak regions, continues to lead in quality-driven aging. North America acts as the primary hub for the American oak barrel market, supported by massive distilling hubs. Emerging regions are observing a trend toward importing premium cooperage to bolster their domestic wine and distillery export capabilities.
In-depth Regional Review: Key Geographic Hotspots
The French oak segment remains tethered to stringent regional appellations, forcing competitive dynamics in regions like Bordeaux and Burgundy. Simultaneously, the United States dominates the charred American oak barrel sector. Analysis shows that companies like Midwest Barrel Co. and Kelowna Barrel Company are successfully navigating localized logistical hurdles to serve the specific regional needs of craft wineries and high-volume distillers alike.
Strategic Positioning of Leading Companies
Industry titans like Tonnellerie Allary and T.W. Boswell utilize distinct branding to capture the high-end luxury segment, while McGinnis Wood Products Inc. focuses on supply chain dominance in the raw material space. Strategic positioning for these firms involves vertical integration with forests or long-term forestry management contracts, ensuring a stable supply of fine-grain wood even as the global competition for timber intensifies.
Porter's Five Forces: Competitive Assessment
The Oak Barrels Market faces moderate threat from substitutes, but high switching costs in premium spirits aging provide a protective moat. Buyer power is concentrated in large distillery conglomerates, putting pressure on mid-tier cooperages to differentiate through proprietary toasting profiles. Meanwhile, supplier power is influenced by forestry regulations, necessitating a proactive approach to sustainable wood procurement to maintain long-term competitive viability.
SWOT Analysis of the Global Oak Barrel Industry
Strengths: Deep-rooted tradition and non-replicable flavor impact. Weaknesses: Sensitivity to timber price volatility and supply chain fragmentation. Opportunities: Rapid growth in the craft alcohol sector and R&D into experimental flavor-enhancing barrels. Threats: Increasing regulatory scrutiny on timber sourcing and the potential for technological innovation in non-wood aging alternatives that could disrupt specific mid-market segments.
Value Chain Analysis: From Forest to Glass
The value chain begins with sustainable forest management, followed by stave production and seasoning, often spanning years. Value is added during the cooperage assembly and toasting/charring phases, where specific expertise creates the desired wood extract profiles. Finally, the supply chain flows to distilleries and wineries, where the barrel becomes an essential, multi-year asset in the production of high-value, aged liquid commodities.
Investment Insights and High-Potential Areas
Our research indicates that the most lucrative investment opportunities reside in reconditioned and refurbished oak barrels and small-batch craft aging vessels. Companies that provide customization—specifically in toast levels and charring intensity—are well-positioned to capture higher margins. Strategic investors should monitor Tonnellerie Baron and Barriles la Arboleda SA DE C.V. for their focus on integrating high-end craftsmanship with modern supply chain efficiency.
Conclusion and Key Takeaways for Stakeholders
The Oak Barrels Market is evolving toward a high-value, innovation-heavy future. With a growth path toward 4.91 Billion by 2033, the industry is no longer just about wood—it is about precision engineering of flavor. Stakeholders must prioritize sustainable wood procurement, embrace experimental aging techniques, and leverage the premiumization trend to maintain a competitive advantage in a consolidating global market.
Research Methodology: How Baseline Estimates were Triangulated
Our methodology employs a triangulation approach, combining verified trade registry data from key ports with primary stakeholder interviews across the top 20 global cooperages. We cross-reference these findings with secondary macroeconomic indicators regarding alcohol consumption and forestry output. This rigorous, multi-layered research ensures that our projections account for both regional nuances and the broader global supply chain complexities inherent in this specialized market.
Scope of the Report and Coverage Parameters
This analysis covers the global Oak Barrels Market, focusing on major barrel types including French, American, Hungarian, and Eastern European oak. It examines the entire value chain, from raw material sourcing to end-use applications in wine, spirits, and beer. The report excludes non-wood aging vessels to ensure a laser-focus on the specific competitive dynamics and growth opportunities within the traditional cooperage industry.
Recent Developments and Industry Strategic Moves
Recent activity highlights a surge in partnerships between cooperages and craft distilleries to develop experimental and R&D barrels. Notable moves include facility expansions by firms like G & P Garbellotto S.p.A, focusing on large-format aging vessels. These strategic shifts reflect a broader industry push to diversify product portfolios, moving from standard formats to bespoke solutions for the rapidly evolving boutique winery and micro-distillery segments.